Smartest Investments Right Now: Debt, Index Funds, Metals
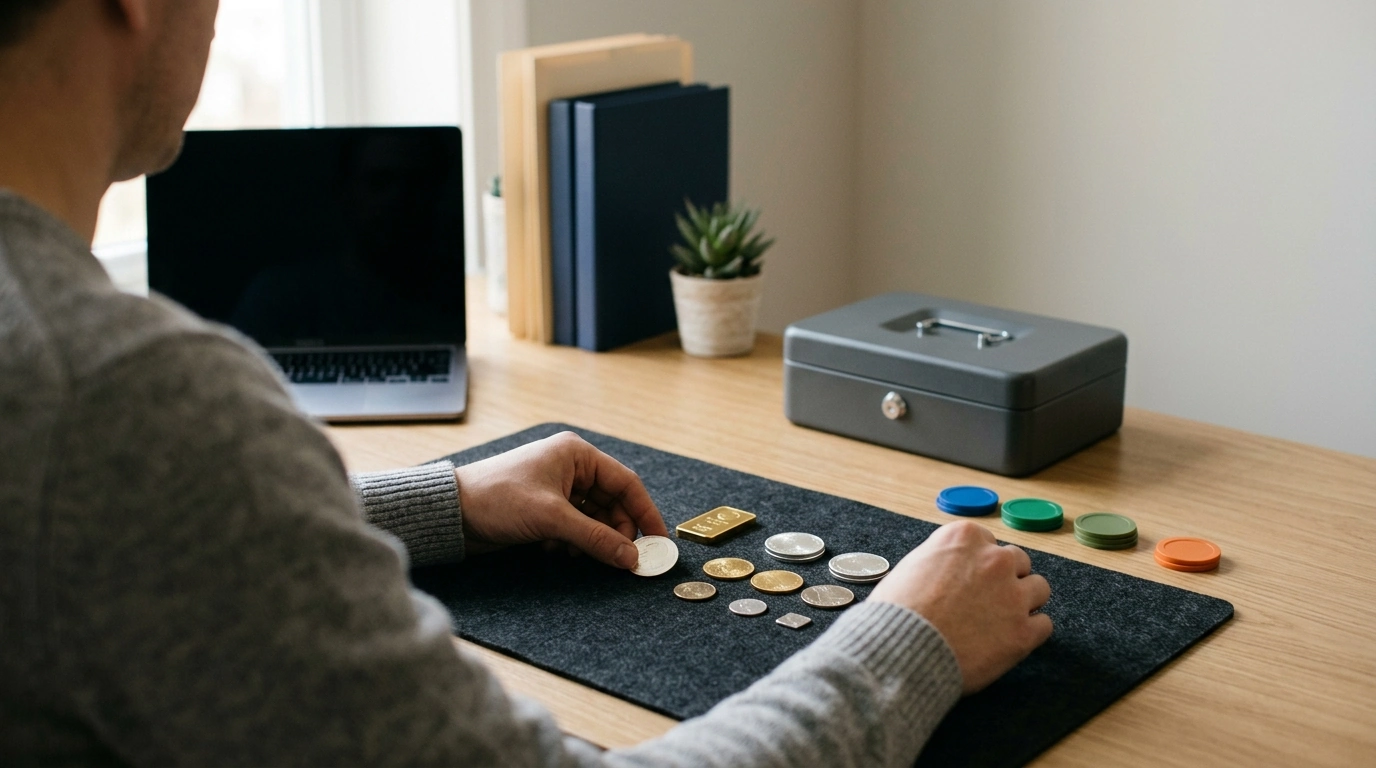
What is the smartest thing to invest in right now?
The smartest investment “right now” is usually the one that strengthens your finances no matter what the market does next: a mix of high-impact basics (cash flow, emergency savings, and debt control) plus diversified, low-cost long-term assets.
Start with a guaranteed return: high-interest debt and cash reserves
If you’re carrying credit card balances or other high-interest debt, paying that down can outperform most market investments because the “return” is the interest you stop paying. Next, build an emergency fund (often 3–6 months of essential expenses) so you don’t have to sell investments at a bad time when life happens.
Capture employer matches and use tax-advantaged accounts
If you have access to a 401(k) match, it’s hard to beat: the match is an immediate boost to your contribution. After that, consider tax-advantaged accounts (like IRAs or HSAs if eligible) to keep more of your compounding growth.
For long-term growth, prioritize diversified, low-cost index funds
For many shoppers and new investors, broad stock and bond index funds are a practical core because they spread risk across hundreds or thousands of companies and typically come with low fees. A simple allocation aligned to your time horizon can be “smart” even when headlines feel uncertain.
Add resilience: consider precious metals as a hedge
If your goal includes protection against inflation, currency risk, or market stress, precious metals can play a supporting role alongside traditional assets. The key is to size the position appropriately and choose a straightforward approach. For a beginner-friendly breakdown, see this guide: precious metals investing for beginners (simple plan).
What makes an investment smart for you
The smartest move depends on your timeline, stability of income, and tolerance for swings in value. A good rule: cover essentials first, build a diversified core, then layer in hedges like precious metals if they fit your plan.
FAQ
How much of a portfolio should be in precious metals?
Many portfolios keep precious metals as a smaller slice rather than the main holding, often to hedge risk instead of drive growth. The right percentage depends on your goals, how volatile other holdings are, and whether you want more stability or more upside.



Leave a comment